

FINTRAC UNIVERSAL ENROLMENT
Universal enrolment
is coming for every FINTRAC reporting entity.
Under Bill C-12 every reporting entity that has AML responsibilities must enrol with FINTRAC. This change is not yet in force, but when it is, all reporting entities (not just MSBs) will be required to enrol with FINTRAC.
what is universal enrolment under bill c-12?
Bill C-12 received Royal Assent on March 26, 2026 and introduced various changes to the Proceeds of Crime (Money Laundering) and Terrorist Financing Act (PCMLTFA) - including, a new Universal Enrolment Framework.
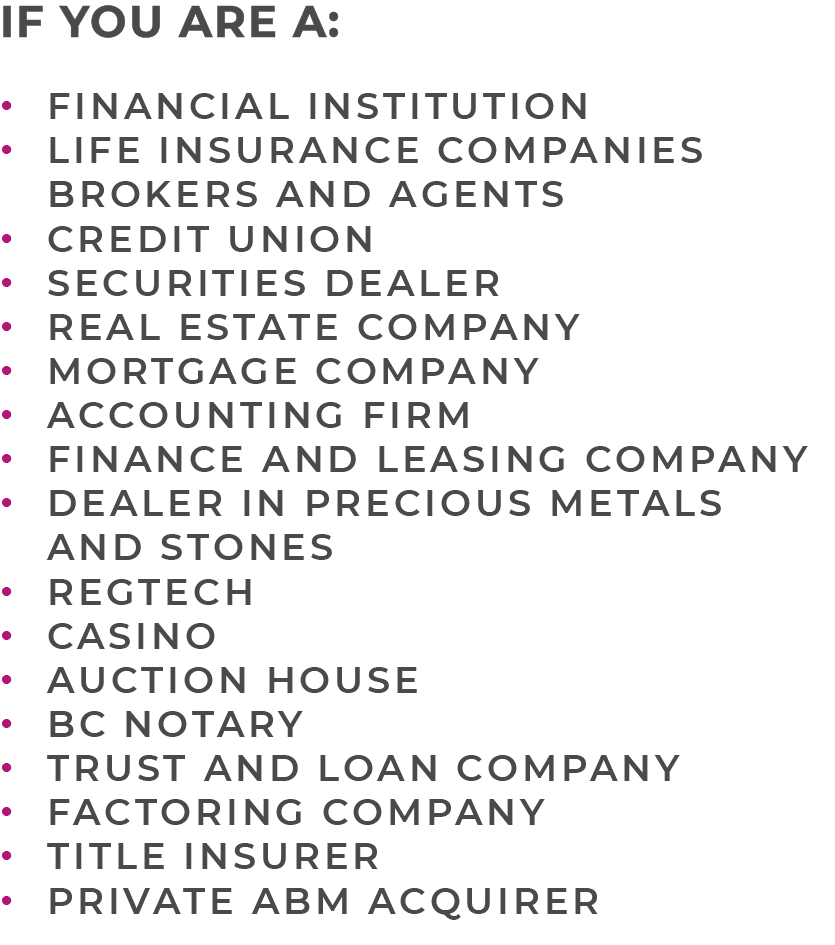
This means mandatory FINTRAC registration for every reporting entity subject to the PCMLTFA, not just Money Services Businesses (MSBs). Universal enrolment extends the obligation across the full range of reporting entities including: financial institutions, life insurance companies, credit unions, securities dealers, trust and loan companies, real estate companies, mortgage companies, title insurers, BC notaries, accounting firms, finance and leasing, factors, dealers in precious metals and stones, RegTech, casinos, private ABM acquirers, and auction houses.
Enrolment coming in to force will be “coming soon” and every single reporting entity needs to be prepared. The AML Shop can help your business navigate these new enrolment requirements.
Important Note: this new mandatory enrolment requirement is not the same as your business being registered for tech access with FINTRAC’s systems in which you may already be enrolled in. Any business that currently reports to FINTRAC uses their tech systems; presumably, yours may already do so. Universal Enrolment is a new animal - think about the extra steps that MSBs have had to take to enrol with FINTRAC… if you are in a different reporting sector, soon you will be required to do the same.
Bill C-12 Compliance: FINTRAC PENALTIES, effectiveness and universal enrolment
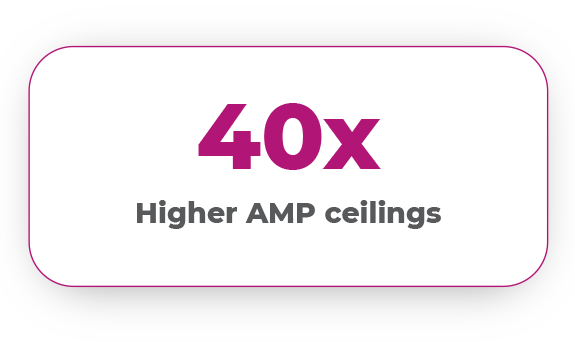
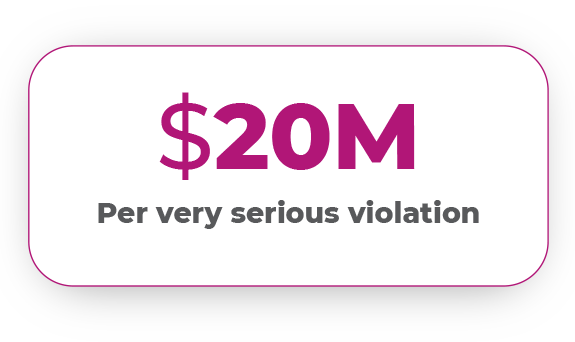
Bill C-12 didn't just add a universal enrolment requirement — it substantially raised FINTRAC's administrative monetary penalties (AMPs) framework, and elevated compliance expectations; programs are now expected to be reasonably designed, risk-based, and effective, not just present on paper. Compliance programs must be proven effective.
By design, enrolment and enforcement are connected. A complete registry of reporting entities allows FINTRAC to plan examinations and identify entities that it has never engaged with - which is why FINTRAC examination readiness also matters well before your first enrolment notice or compliance questionnaire arrives.
what TO EXPECT WHEN FINTRAC UNIVERSAL ENROLMENT TAKES EFFECT
When the enrolment framework as outlined under BIll C-12 is in force, expect FINTRAC and industry associations to actively identify entities that have yet to enrol, but are obligated to do so (that’s everyone!) — likely through direct notices, "have you registered?" campaigns, and messaging from trade associations, reinforcing the requirement. Before you know it, the push to enrol will be everywhere.
Some entities will receive these notices without ever having had a prior relationship with FINTRAC, and won't know what's being asked of them, whether they're in scope, or how to respond…and often on a compressed timeline. The AML Shop can help you navigate these requests in an accurate and timely manner - whether you are already engaging with FINTRAC or need to get started.
how THE AML SHOP HELPS
Assess whether your business has AML responsibilities
Preparation and management of your FINTRAC enrolment application
Guidance for responding to FINTRAC notices and compliance questionnaires
Develop and craft compliance programs that meet Bill C-12’s "reasonably designed, risk-based, and effective" standard
Support your business through FINTRAC examinations and inquiries
faqs
-
Bill C-12 received Royal Assent on March 26, 2026, so it is law. Universal enrolment specifically is not yet in force. It will take effect when supporting regulations are published.
-
If your business falls under the PCMLTFA — including sectors like real estate, mortgage, credit unions, casinos, life insurance companies, financial institutions and securities dealers — you are a reporting entity, even if you have never enrolled with FINTRAC before. Note, currently all Money Services Businesses (MSBs), including payments companies, Virtual Currency, and others, are required to enrol with FINTRAC.
-
Non-enrolment is expected to be an enforceable violation, separate from any other compliance gaps FINTRAC identifies once you're on the radar.
-
Review it carefully before responding, how you answer sets the tone for your relationship with FINTRAC. The AML Shop can review it with you first. contactus@theamlshop.ca to get started.
KEY CONTACTS

Mark Ambrose - Principal, Anti-Financial Crime and Regulatory Compliance
mark@theamlshop.ca
LinkedIn
Mark is an experienced compliance and financial crime risk professional with more than 30 years in financial services, including service as Chief Compliance Officer (CCO) and Chief Anti-Money Laundering Officer (CAMLO). He supports Canadian financial services businesses, including credit unions in enhancing compliance programs, mitigating regulatory risk, and responding effectively to supervisory oversight. Read more.

Marcelle Dadoun - Principal, Program Design and Advisory
marcelle@theamlshop.ca
LinkedIn
Marcelle Dadoun, Principal, Program Design and Advisory leads The AML Shop's compliance program design division and provides advisory support to all reporting types, including new and evolving money services businesses, payment service providers and fintech clients looking to navigate local and international regimes for registration, licensing, and regulations. Read more.

Michael Ecclestone - Principal, Regulatory Assessments
michael@theamlshop.ca
LinkedIn
Michael is Governance, Risk and Compliance Leader at The AML Shop, with over 20 years of experience in financial sector risk, regulatory compliance and legislation as an advisor, an executive, a regulator and a practicing lawyer. Throughout his career he has specialized in resolving complex regulatory issues, leveraging his uniquely broad and deep knowledge of financial services law and regulatory frameworks around the world. Read More

Adam Feldman - Principal, Risk Management and Technology
adam@theamlshop.ca
LinkedIn
Adam Feldman leads The AML Shop's risk management and technology divisions and is recognized as a specialist in the real estate, mortgage and financing, and professional services sectors…read more
QUICK LINKS